
Gray Divorce in Texas
Gray Divorce in Texas: Navigating Divorce After 50 in Collin County
Ending a marriage after decades together is a profound transition. While overall divorce rates have stabilized across the United States, the rate of gray divorce in Texas, divorces involving spouses aged 50 and older—has surged over the past two decades. Empty nesters, pre-retirees, and seniors across McKinney, Frisco, Fairview, and Plano are increasingly choosing to begin new chapters in the second half of life.
However, a divorce after 50 in Texas presents legal and financial realities distinct from a divorce in your 30s or 40s.
When you divorce later in life, child custody battles are often replaced by high-stakes retirement calculations, complex estate restructuring, healthcare coverage concerns, and long-term financial security. Most importantly, older spouses face a limited timeline to recover from financial missteps, making strategic legal planning essential.
Below, we break down the unique complexities of late-life divorce in Collin County, how long-term assets are divided, and how you can safeguard your retirement lifestyle.
The “Zero-Recovery Horizon”: Why Gray Divorce Demands a Unique Strategy
When younger couples divorce, they have decades of peak career earnings ahead to rebuild savings, repay debt, and contribute to retirement accounts. In contrast, spouses navigating a gray divorce face what financial planners call the “Zero-Recovery Horizon.”
If you are within 5 to 15 years of retirement—or already retired—you have limited time to replenish depleted investment portfolios or recover from an unfavorable property settlement. A single oversight in valuing pensions, liquidating real estate, or accounting for tax liabilities can permanently impair your retirement security.
Dividing Retirement in Texas Divorce Over 50: 401(k)s, IRAs, and Pensions
Under the Texas Family Code, all retirement benefits accumulated during the marriage are community property subject to a “just and right” division. In long-term marriages spanning 20, 30, or 40 years, retirement assets often represent the largest portion of the marital estate.
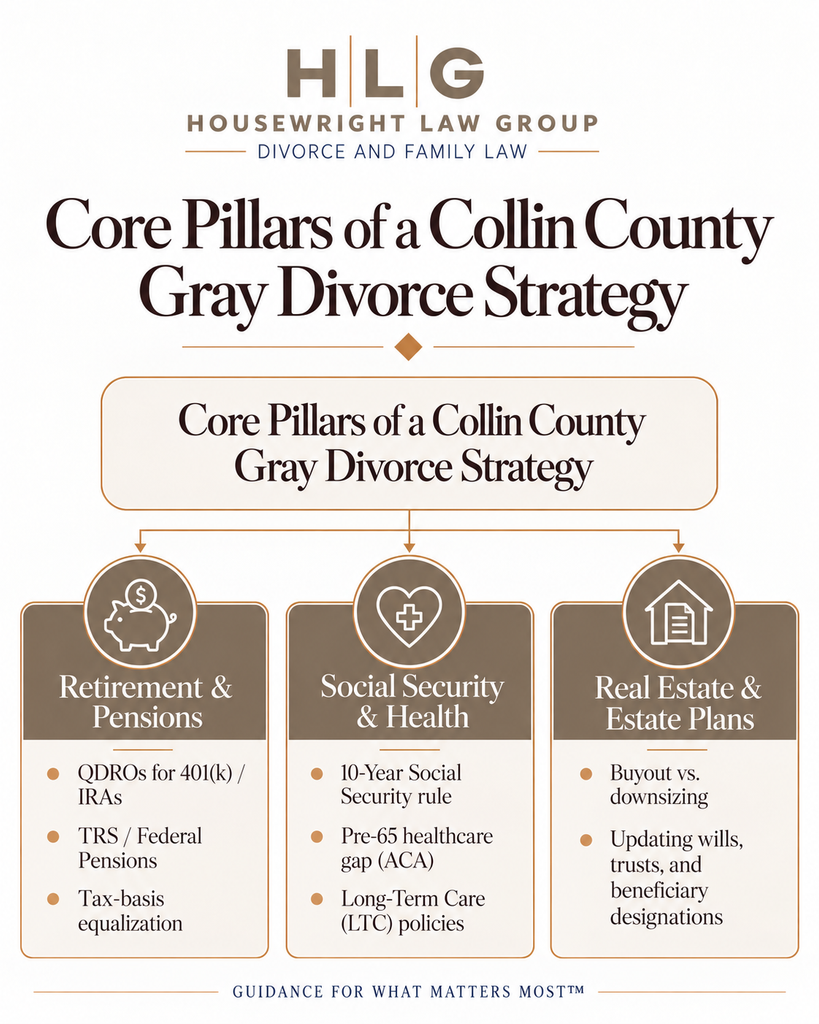
1. Splitting 401(k)s, 403(b)s, and IRAs via QDROs
When dividing retirement in texas divorce over 50, funds cannot simply be transferred from one spouse’s account to another without triggering severe tax consequences.
- Qualified Domestic Relations Orders (QDROs): A QDRO is a specialized court order that instructs the retirement plan administrator to assign a specific percentage or dollar amount to the non-employee spouse (the “alternate payee”).
- Direct Rollovers: The alternate payee can roll their awarded share directly into their own traditional IRA without paying early withdrawal penalties or immediate income taxes.
- Tax Basis Equalization: Not all retirement dollars are equal. A $500,000 balance in a traditional pre-tax 401(k) carries deferred income tax liabilities, whereas $500,000 in a post-tax Roth IRA or standard brokerage account does not. A skilled legal team ensures tax parity when balancing asset divisions.
2. State, Municipal, and Federal Pensions (TRS, Military, Civil Service)
Many long-term North Texas residents have dedicated careers to public education, municipal government, or military service. Defined-benefit pensions—such as the Teacher Retirement System of Texas (TRS) or military retired pay—must be divided using strict statutory formulas.
Texas courts utilize the Taggart or Berry apportionment formulas to calculate the exact community share of the pension earned during the marriage. Because these systems have unique administrative requirements, specialized drafting is required to ensure survivor annuities and monthly benefit payouts are properly secured.
Social Security Spousal Benefits: What You Need to Know
For many divorcing spouses over 50, understanding social security spousal benefits divorce texas rules provides significant peace of mind.
Under federal Social Security Administration (SSA) regulations, you can receive derivative benefits based on your former spouse’s work record if you meet specific criteria:
- The 10-Year Marriage Rule: Your marriage must have lasted for at least 10 consecutive years.
- Age Requirement: You must be at least 62 years old and currently unmarried.
- Benefit Comparison: The benefit you are entitled to receive based on your own work record must be less than the benefit you would receive based on your former spouse’s record.
Key Facts About Derivative Social Security Benefits:
- Zero Impact on Your Ex-Spouse: Claiming benefits on your former spouse’s earnings record does not reduce their monthly benefit, nor does it impact what their current spouse (if they remarry) can receive.
- No Direct Negotiation Required: Social Security is governed entirely by federal law; it cannot be traded away, divided, or modified in your Texas divorce decree.
- Independent Access: You apply directly through the Social Security Administration without needing your ex-spouse’s consent or participation.
Bridging the Healthcare and Insurance Gap Before Age 65
In many long marriages, one spouse has historically provided health insurance coverage through an employer group plan. When the divorce is finalized, the non-employee spouse loses dependent coverage under that policy.
If you divorce before age 65 (when Medicare coverage begins), securing reliable healthcare coverage is a critical budget priority:
- COBRA Coverage: Federal COBRA laws allow a divorced spouse to remain on the former spouse’s employer health plan for up to 36 months. However, the individual must pay the full premium cost (often $700 to $1,200+ monthly), making this an expensive interim solution.
- ACA Marketplace Plans: Finalizing a divorce triggers a Special Enrollment Period (SEP) on the Affordable Care Act (Healthcare.gov) marketplace, allowing you to secure individual coverage outside standard open-enrollment windows.
- Long-Term Care (LTC) Insurance: If the couple purchased joint long-term care insurance policies during the marriage, the divorce agreement must address who will continue paying premiums and how benefits will be restructured to protect both individuals as they age.
Downsizing the Family Home and Restructuring Estate Plans
In affluent Collin County communities like McKinney, Fairview, and Frisco, long-term marital residences often have significant equity or are fully paid off. Deciding what to do with the home is a pivotal financial decision.
1. Marital Residence: Sell vs. Buyout
While emotional attachment to a long-time family home is natural, keeping a large property may not make financial sense. Maintaining a home involves substantial property taxes, HOA fees, insurance, and ongoing maintenance on a single income.
- Selling and Splitting Equity: Frequently, selling the property and dividing the tax-exempt net proceeds provides both spouses with liquid capital to purchase manageable single-story homes or townhomes in North Texas.
- Refinancing for Buyouts: In higher interest rate environments, buying out a spouse’s equity and refinancing an existing low-rate mortgage into a sole name requires careful debt-to-income analysis.
2. Overhauling Estate Planning Documents
Under Texas Estates Code § 123.001, a final divorce automatically revokes provisions in your will that leave property to your former spouse. However, relying on statutory default rules is risky. Immediately upon filing—and following the final decree—you must comprehensively update:
- Last Will and Testament and Revocable Living Trusts.
- Durable Financial Powers of Attorney and Medical Directives.
- Beneficiary designations on life insurance, IRAs, 401(k)s, and Transfer-on-Death (TOD) bank accounts.
Protect Your Next Chapter with a McKinney Divorce Lawyer
A gray divorce is not merely the end of a marriage; it is the financial reorganization of your entire life’s work. The decisions made during this process will dictate your lifestyle, healthcare, and financial independence throughout your retirement years.
At Housewright Law Group, we provide sophisticated, empathetic, and strategic representation tailored to the unique needs of older spouses. Whether your case involves complex pension valuation, business equity, real estate division, or spousal maintenance, an experienced McKinney divorce attorney from our team is prepared to protect your assets and advocate for your long-term security.
We guide you through every financial detail so you can step into your retirement years with confidence and peace of mind.
Secure your financial future today. Contact Housewright Law Group to schedule a confidential consultation at our McKinney office. Let us help you navigate your late-life divorce with clarity and strength.